Institutional FX Insights: Credit Agricole FX Weekly 18/9/26
G10 Central Banks vs. Supply Shocks & Yield Curve Inversion Risks
THE TAKE: CENTRAL BANKS FIGHT SUPPLY-SIDE INFLATION AT GROWTH'S EXPENSE
Global central banks are aggressively tightening into a severe supply-side inflation trifecta: energy shocks from the US-Iran conflict, metal price surges driven by the global AI data centre buildout, and agricultural pressures from El Niño. With productivity growth remaining subdued, central banks risk over-tightening ("breaking their economies") to tame inflation caused by supply constraints rather than demand overheating.
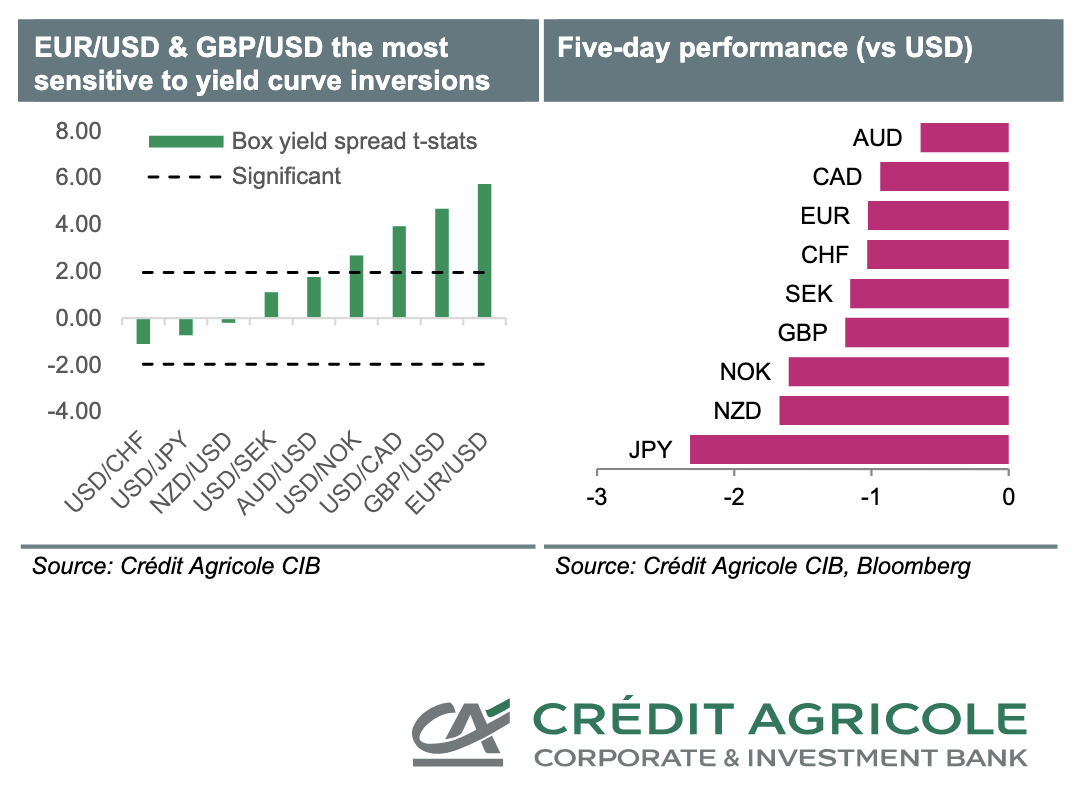
FX VULNERABILITY TO OVER-TIGHTENING (BOX YIELD SPREAD SENSITIVITY)
Looking at exchange rate sensitivity to box yield spreads (relative slopes of yield curves, tracking yield curve inversions via FAST FX models), G10 currencies exhibit vast differences in vulnerability to policy over-tightening:
High Sensitivity (Most Vulnerable to Yield Inversion):
EUR/USD: Most sensitive among G10 USD crosses to yield curve inversion.
GBP/USD & USD/CAD: High structural sensitivity to relative yield curve flattening/inversion.
Moderate Sensitivity:
USD/NOK: Moderate sensitivity; last cross where the box yield spread remains a statistically significant driver.
Low / Insignificant Sensitivity:
AUD/USD & USD/SEK: Limited box spread sensitivity.
USD/JPY, NZD/USD & USD/CHF: Exhibit small, negative, and statistically insignificant correlations with box yield spreads.
CENTRAL BANK POLICY MATRIX & UPCOMING CATALYSTS
Recent Rate Hikes:
Federal Reserve (Fed): Hiked +25 bps to 3.75%–4.00%, signaling higher-for-longer commitment.
Bank of Japan (BoJ): Hiked rates to counter inflation and currency weakness.
European Central Bank (ECB): Hiked rates in prior session to anchor expectations.
Pause / Mixed Signals:
Bank of England (BoE): Held rates steady in September; slowed Quantitative Tightening (QT) pace, dampening hawkish rhetoric.
Upcoming Decision Pipeline:
Riksbank & Norges Bank: Decision on deck (potential hawkish surprise for Riksbank).
Swiss National Bank (SNB): Expected to make subtle hawkish tweaks away from dovish stance.
Reserve Bank of Australia (RBA): Expected to deliver its 4th rate hike of the year next week, informed by upcoming Australian employment data.
KEY CATALYSTS FOR THE WEEK AHEAD
PMI Datapoints (Eurozone, Japan, US, UK): Gauges underlying economic momentum entering the latest wave of central bank tightening.
Geopolitical Risk (Trump-Xi Washington Summit): High stakes for trade policy; market looking to avoid renewed bilateral trade friction that would compound inflation pressures.
Central Bank Communications: Speeches scheduled from ECB, Fed, BoC, BoE, and RBA officials to gauge appetite for further tightening.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% and 73% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!